Regular investing, explained
Why so many investors put in a fixed amount every month — with worked examples of compounding and cost averaging — and how FolioCenter’s Investment Plans keep your history complete without re-entering every contribution.
What regular investing is
Regular investing means putting in a fixed amount at fixed intervals — say €200 at the start of every month — whatever the market is doing. It matches how most people earn: a salary arrives monthly, so savings can too. You may know it as cost averaging, dollar-cost averaging, or simply a savings plan.
Small amounts add up
The most visible effect is compounding: returns earned on earlier contributions start earning returns of their own. Here is what €200 a month for 20 years — €48,000 put in — would grow to at a few constant annual rates. The rates are illustrations, not predictions: real returns vary from year to year and can be negative.
| Annual return (illustrative) | Value after 20 years | Of which growth |
|---|---|---|
| 0% | €48,000 | €0 |
| 3% | €65,660 | €17,660 |
| 5% | €82,207 | €34,207 |
| 7% | €104,185 | €56,185 |
Monthly contributions with monthly compounding, before fees and taxes.
Time does much of the work: at 7%, more than half of the final value is growth rather than money put in. Starting earlier matters more than the size of any single contribution.
Cost averaging: more shares when prices are low
A fixed amount buys more shares when the price is low and fewer when it is high. Say you invest €100 a month for five months while the price moves from €10 down to €5 and back:
| Month | Price | Invested | Shares bought |
|---|---|---|---|
| 1 | €10 | €100 | 10.0 |
| 2 | €8 | €100 | 12.5 |
| 3 | €5 | €100 | 20.0 |
| 4 | €8 | €100 | 12.5 |
| 5 | €10 | €100 | 10.0 |
| Total | €500 | 65.0 |
The average price over the five months was €8.20, but your average cost is €7.69 a share. With the price back at €10, your €500 is worth €650 — even though the price only returned to where it started.
The honest trade-off. Had the price risen steadily instead, investing all €500 in month one would have bought more shares at lower prices. In markets that mostly rise, investing a lump sum early has often come out ahead. Regular investing is less about beating that and more about not having to guess the right moment.
Why many investors invest regularly
- No need to time the market. Nobody reliably knows the best day to buy; a schedule takes the question away.
- A habit, not a decision. Investing becomes as routine as paying a bill, which makes it easier to keep going through bad months.
- Less regret. Falling prices become a chance to buy more cheaply rather than a reason to stop.
- It fits a monthly income. You invest what you earn as you earn it, rather than waiting to build up a large sum.
It has limits too: small purchases can be expensive if each one carries a fee, it does not protect against a long decline, and it works best with a diversified investment.
How Investment Plans work in FolioCenter
An Investment Plan records your regular transactions for you, so your history and your returns stay complete without typing in every contribution. FolioCenter does not move money or place orders: the deposit and the purchase still happen at your bank and broker, and the plan keeps FolioCenter in step with them.
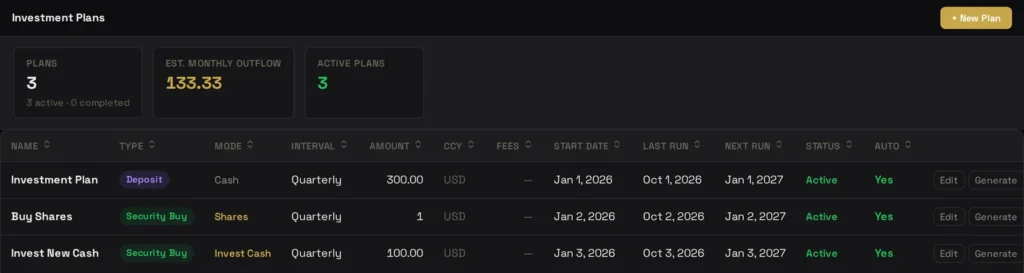
Choose an amount mode, then a plan type:
| Mode | Plan type | What it records each time |
|---|---|---|
| Cash | Deposit | Money paid into an account or a savings account |
| Cash | Removal | Money taken out of an account — a regular withdrawal |
| Cash | Interest | A fixed interest payment credited to an account |
| Shares | Security Buy | A fixed number of shares bought at the latest price, with the cash that pays for them |
| Shares | RSU Grant (coming soon) | A new RSU grant, with its vesting schedule |
| Invest Cash | Security Buy | A fixed amount of cash paid in and invested at the latest price — as many shares as it buys |
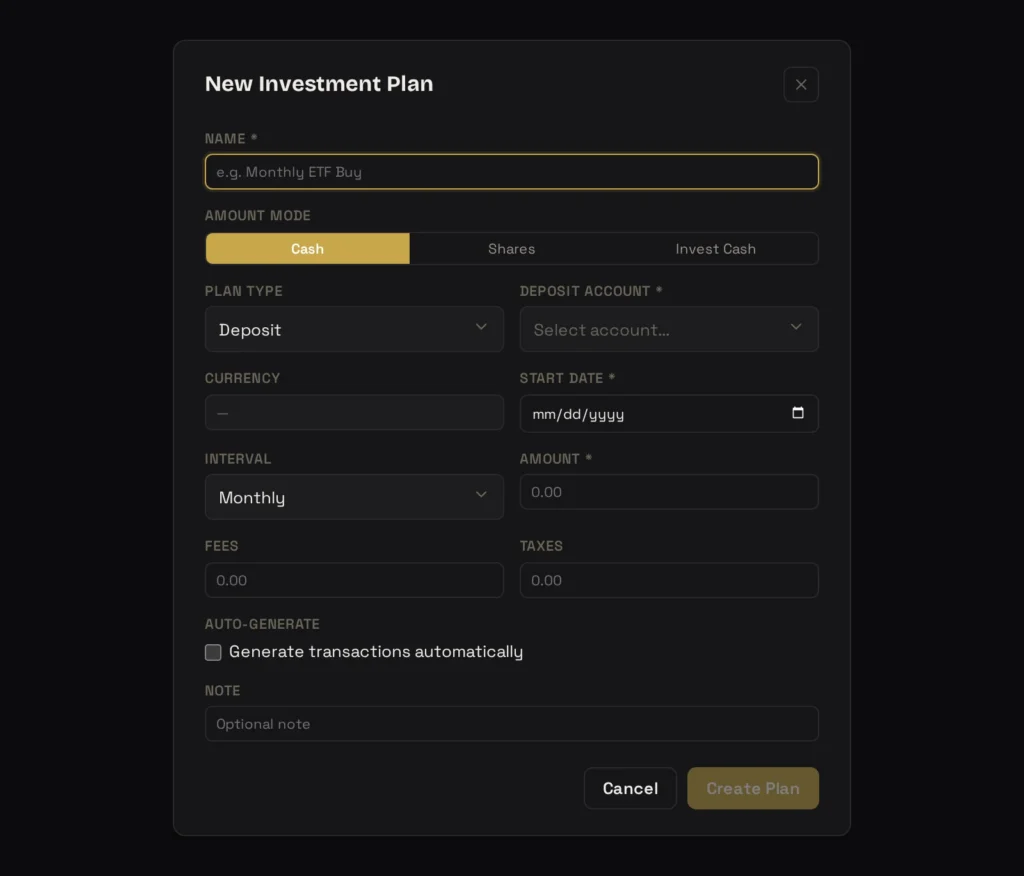
Plans run weekly, every two weeks, monthly, quarterly, every six months or yearly, from the start date you choose. You can record fees and taxes on every run, and for Invest Cash plans allow fractional shares — or buy whole shares and keep the remainder as cash, as many brokers do.
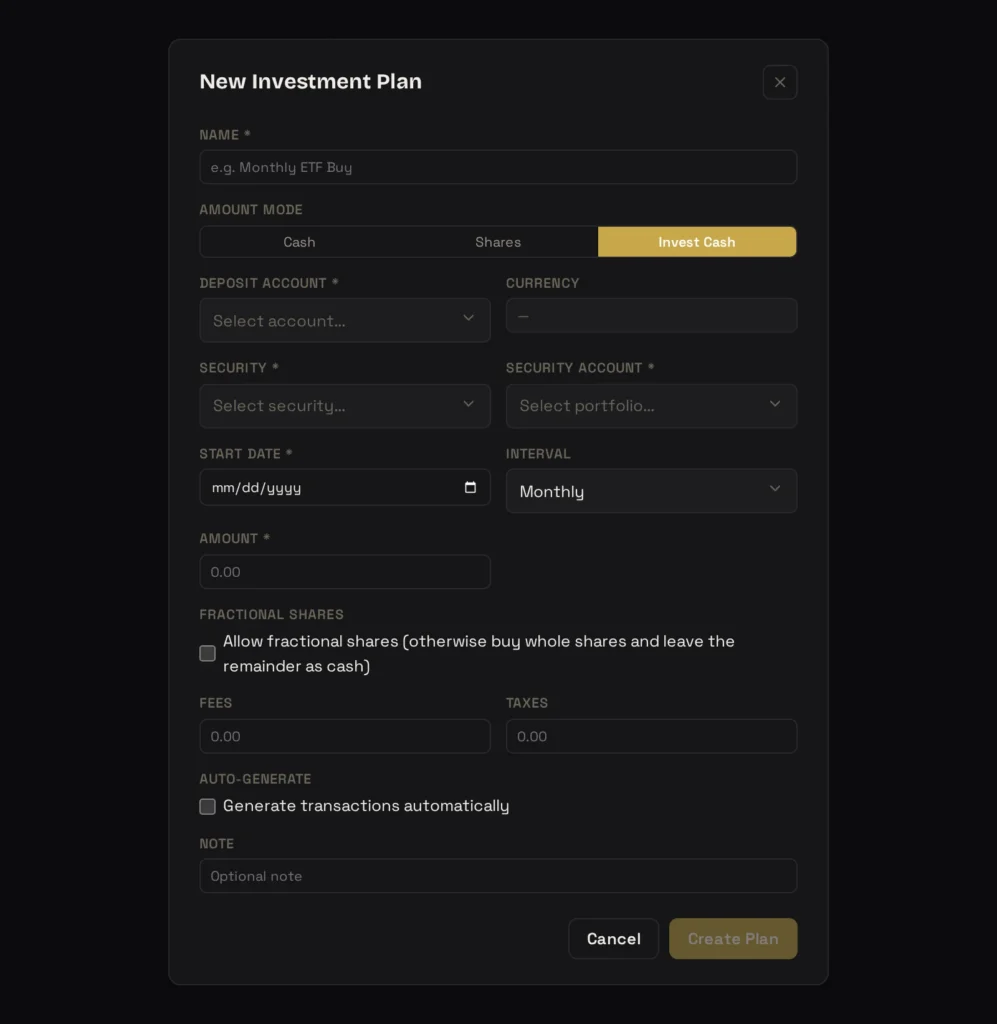
Tick Generate transactions automatically and FolioCenter records each run overnight when it falls due — including any runs missed since the start date. Leave it unticked to stay in control: the Generate button records a run whenever you choose. Every recorded transaction is an ordinary one, so you can adjust its price or fees to match your broker’s statement.
Common questions
No. FolioCenter never connects to your broker or moves money. The plan records the transactions that your own standing order or broker savings plan carries out, so your portfolio in FolioCenter stays up to date.
The latest price FolioCenter has for the security when the run is recorded. If your broker filled the order at a different price, edit the transaction to match your statement.
With automatic generation on, FolioCenter catches up and records every run between the start date and today.
No. Deposits and withdrawals are money moving in and out, not gains or losses. Time-weighted return sets them aside; money-weighted return accounts for when each one arrived. See TWROR & IRR explained.
Yes. Edit the plan to change its amount or interval, or switch it off. Transactions already recorded stay in your history.
Keep your history complete, automatically
Set up your regular contributions once and see their effect on your returns, month after month.
Start free →Already have an account? Sign in
The examples on this page are illustrations, not forecasts. Regular investing does not guarantee a profit or protect against losses, and this guide isn’t investment advice.